The dangers of drawing neural lines in the sand
PM: You got five minutes?
IW: For you? Always. For the bi-polar market? Less so…
PM: Clients are spooked again. Another sentiment-y sell-off. Everyone wants a clean label: “risk-off,” “AI panic,” “macro scare,” pick your poison. I need something that calms the noise.
IW: So you want… a kind of ‘ode to nuance’?
PM: I guess so. But don’t make me regret saying that.
IW: The problem isn’t the sell-off. The problem is the categorisation reflex. People reach for a box, any box, just to stop the discomfort.
PM: Because discomfort is cognitively expensive.
IW: Exactly. Oliver Burkeman has a whole thing on this. The “death of nuance” isn’t just cultural; it’s neurological. We’re wired for snap judgements, not patient ambiguity.
PM: Our brains are basically interns: eager, undertrained and desperate to file things somewhere.
IW: And once filed, we defend the folder name.
PM: Which is what I’m seeing in markets. “AI winners,” “AI losers.” As if it’s a binary and not a messy spectrum of second-order effects.
IW: The burden of binary brains in a complex world. Kevin Dutton basically wrote the diagnosis on the cover: Black-and-White Thinking. And then the subtitle is the prescription – “learn to think in technicolour.”
PM: Technicolour. I like that.
IW: The behavioural biologist Robert Sapolsky really makes you feel it. He opens Behave with colour perception – the light spectrum is continuous, genuinely unbroken, but different languages slice it at different points. Russian speakers have separate words for light blue and dark blue. Some languages bundle blue and green together. The photons don’t change when you cross a border. Only the label does.
PM: And we argue as if the label is the thing.
IW: As if the category is nature. Which is exactly what’s happening every time someone says “AI winners” and “AI losers” – as though second-order effects across a continuous competitive landscape somehow resolve into two clean columns.
PM: The burden is real. But we also need heuristics. Without categories, we drown.
IW: True. Our working memory is tiny. You can only hold a few “chunks” at once – Nelson Cowan’s famous argument is closer to 3-4 chunks, not infinite nuance.
PM: And it’s not like long-term memory saves us, either – it isn’t a warehouse. It’s selective, reconstructive scaffolding. We rebuild reality from whatever we can keep hold of.
IW: Which is why two people can look at the same market tape and genuinely inhabit different realities.
PM: Exactly.
IW: Different facts, different anchors and different remembered context. Same tickers, different world.
PM: Give me an example we can use that doesn’t make us sound like we’ve been reading pop-philosophy on company time.
IW: Amazon.
PM: Of course.
IW: Is it e-commerce? A logistics company? A media company? Or a hyperscaler that happens to sell socks on the side?
PM: The answer depends on what you’re trying to explain: revenue, profit, narrative or valuation.
IW: Exactly. And sector classifications force a judgement call that’s half accounting, half politics and half romance.
PM: I can see why you’re an investment writer and not a portfolio manager now. That math is atrocious. Romance seems a stretch, too.
IW: Well, romance requires leaps of faith too. And, please, who actually says math in the singular?
PM: Let’s not get in a class-war discussion. Your point holds, and index providers are basically officiating the identity.
IW: Yes. They’re doing metaphysical illusion with spreadsheets.
PM: And then the truly funny part: passive takes those judgments as gospel. Like it’s the “market,” when it’s really a committee decision with consequences.
IW: Passive is blind by design. It doesn’t choose, it merely obeys. Which is fine until the world changes shape and the rules get stress-tested.
PM: Especially now, with a handful of looming mega-IPOs.
IW: Exactly. A couple of monsters land, and suddenly indices – and every passive product tied to them – have to buy a story at scale.
PM: SpaceX, for one, would distort the plumbing.
IW: It becomes a gravitational event. Passive isn’t “neutral” in that moment. It’s forced demand dressed up as inevitability.
PM: Which is why “we’re all thematic investors now” feels true. Everyone wants to own a story, not a sector.
IW: And stories move faster than meaning.
PM: Meaning is slower to monetise.
IW: New acronyms breed faster than rabbits. TACO, HALO… the market now speaks in memes and four-letter talismans.
PM: “HALO” still annoys me. It sounds like a videogame. Then you look closer and it’s someone trying to rebrand capital intensity as a virtue.
IW: Heavy Assets, Low Obsolescence – a whole worldview stuffed into one neat label.
PM: So what do we tell clients? That the market is lazy?
IW: Not lazy. Bandwidth constrained. People can’t hold the full complexity at once, so they grab a category like a life raft.
PM: Okay, but categories are also useful.
IW: Of course. The mistake is treating them as discrete truths rather than fuzzy tools.
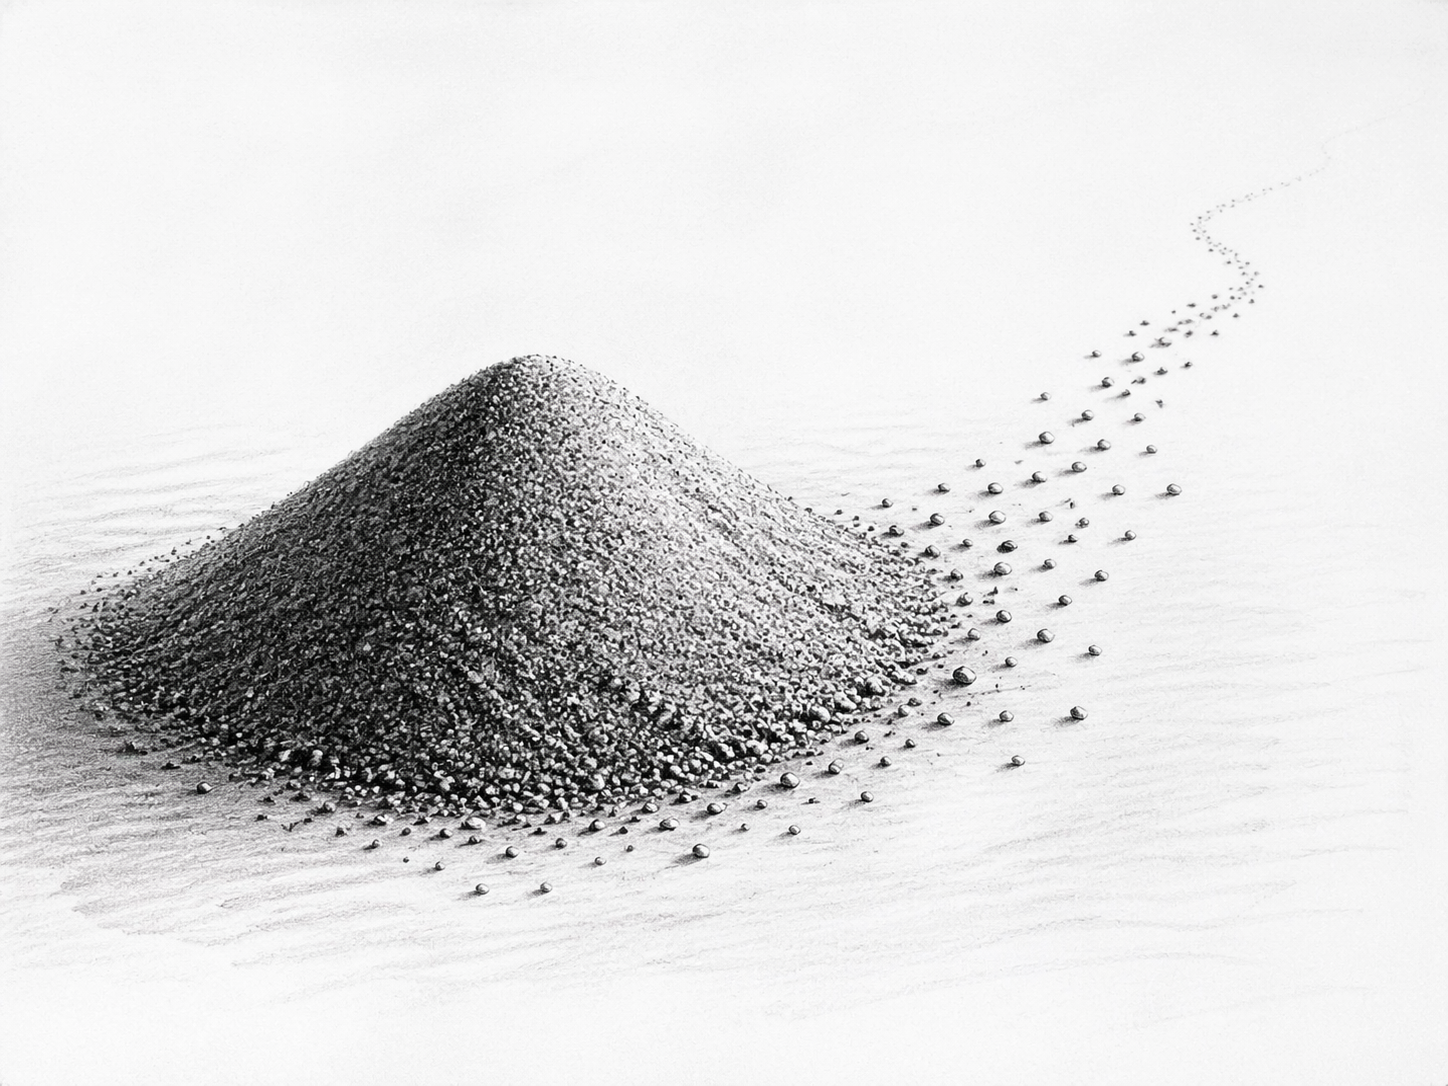
PM: The “sand heap” problem?
IW: Yes – Sorites paradox. How many grains make a heap? And the investing version: when does a “US company” stop being “US” if most revenues are global?
PM: So factor/style labels are just… convenient fiction.
IW: Useful fiction. But, yes, still fiction. Style is a spectrum, not a border patrol.
PM: And the market trades the labels anyway.
IW: That’s the key tension. The market can whipsaw on a label even when the underlying reality didn’t change much.
PM: AI narratives are the best example. Everyone gets overdone. No discernment, no depth – just pendulum swings.
IW: Like the “tyranny of the discontinuous mind”? Richard Dawkins’ famous phrase for our habit of chopping continua into fake bins.
PM: Yep, which is basically what’s happening with every “winner/loser” narrative. We make a clean cut. Then reality turns up in shades.
IW: Exactly.
PM: Oh god. We’re not back to Sapolsky again, are we?
IW: Still with Dawkins, technically. Though they’d agree on the diagnosis. Different culprits, same crime.
PM: Fine. Shades, not switches.
IW: And that’s what makes it exploitable. Distinguish label moves from substance moves – when prices swing on category churn, ask what actually changed. Cash flows? Balance sheets? Competitive position? Or just the story and the bucket? If everyone else is trading the label, the edge is in knowing where the colour actually changed.
PM: And if it’s just the bucket?
IW: Then we treat it as what it is: sentiment and positioning doing what they do – loud, fast and not always smart.
PM: So our “ode to nuance” needs to do two things: validate the discomfort, and remind investors that the labels are not the thing.
IW: Exactly. The discipline is not “no categories,” it’s “hold them lightly.”
PM: Oooh. “Hold them lightly” is good.
IW: That’s because it’s actionable. It’s not “be nuanced” as a moral virtue; it’s “be nuanced” as risk management.
PM: Good. And make sure we don’t sound like we’re complaining that the market is irrational.
IW: No, we’ll sound like adults acknowledging constraints: cognitive constraints, category constraints and liquidity constraints.
PM: And liquidity itself?
IW: Also a continuum. People treat it as a switch: liquid/illiquid. But it’s more like a dimmer, and in stress someone turns it right down.
PM: Great. Send me a draft.
IW: I will. But here’s a sneak peak of the last line: “Markets loves a binary. Our job is to keep seeing the spectrum.”